
Scenario modelling has formed part of our investment philosophy for over two decades, and it enables us to better understand potential market outcomes and construct stronger portfolios. The CAM Asset Management team has a core or “High Conviction” scenario based on a three-year view, which is expressed as macroeconomic and market assumptions, including economic growth, inflation, interest rates, price-earnings multiples, and credit spreads, to list a few. Based on these assumptions, our asset valuation models produce expected returns for various asset classes. This section is used to summarise our High Conviction view and the resulting asset signals.
High Conviction scenario: Medium-term expected returns
Our High Conviction scenario assumes that the global economy will continue to grow close to capacity over the next three years, despite ongoing policy and geopolitical uncertainty. Growth expectations remain broadly unchanged in the United States (US) and emerging markets (EMs), while the outlook for Europe and the United Kingdom (UK) has improved modestly from a low base. Inflation has remained relatively contained at headline level despite higher energy costs and is expected to normalise gradually towards central bank targets.
Policy (interest) rate assumptions have been revised higher across most markets, with modest additional increases expected in some regions before rates are assumed to ease again towards the end of the three-year horizon. Government bond yields rose substantially during the quarter and are now above our fair value assumptions across most major markets, improving medium-term expected returns. Credit spreads remain near historically tight levels. Although these are supported by resilient corporate fundamentals, they limit the potential for additional returns from further spread compression.
The medium-term outlook for global equities remains neutral. Earnings growth is expected to remain solid, while the rise in bond yields and related market weakness has improved valuations across most regions. However, higher bond yield assumptions have also resulted in slightly lower assumed exit price-earnings multiples. Global, US, European, UK, Japanese and EM equities therefore retain neutral signals, with medium-term returns expected to be driven primarily by earnings delivery rather than further valuation expansion.
South Africa’s (SA’s) near-term economic outlook remains subdued but stable, with inflation relatively contained and growth expected to improve gradually. The South African Reserve Bank is expected to deliver a limited additional hiking cycle before easing alongside the broader global rate cycle. SA bond yields remain above our fair value assumption and offer attractive real returns, while the recent SA equity-market weakness has improved valuations. SA enhanced cash, government bonds and equities consequently all carry above-neutral medium-term signals.
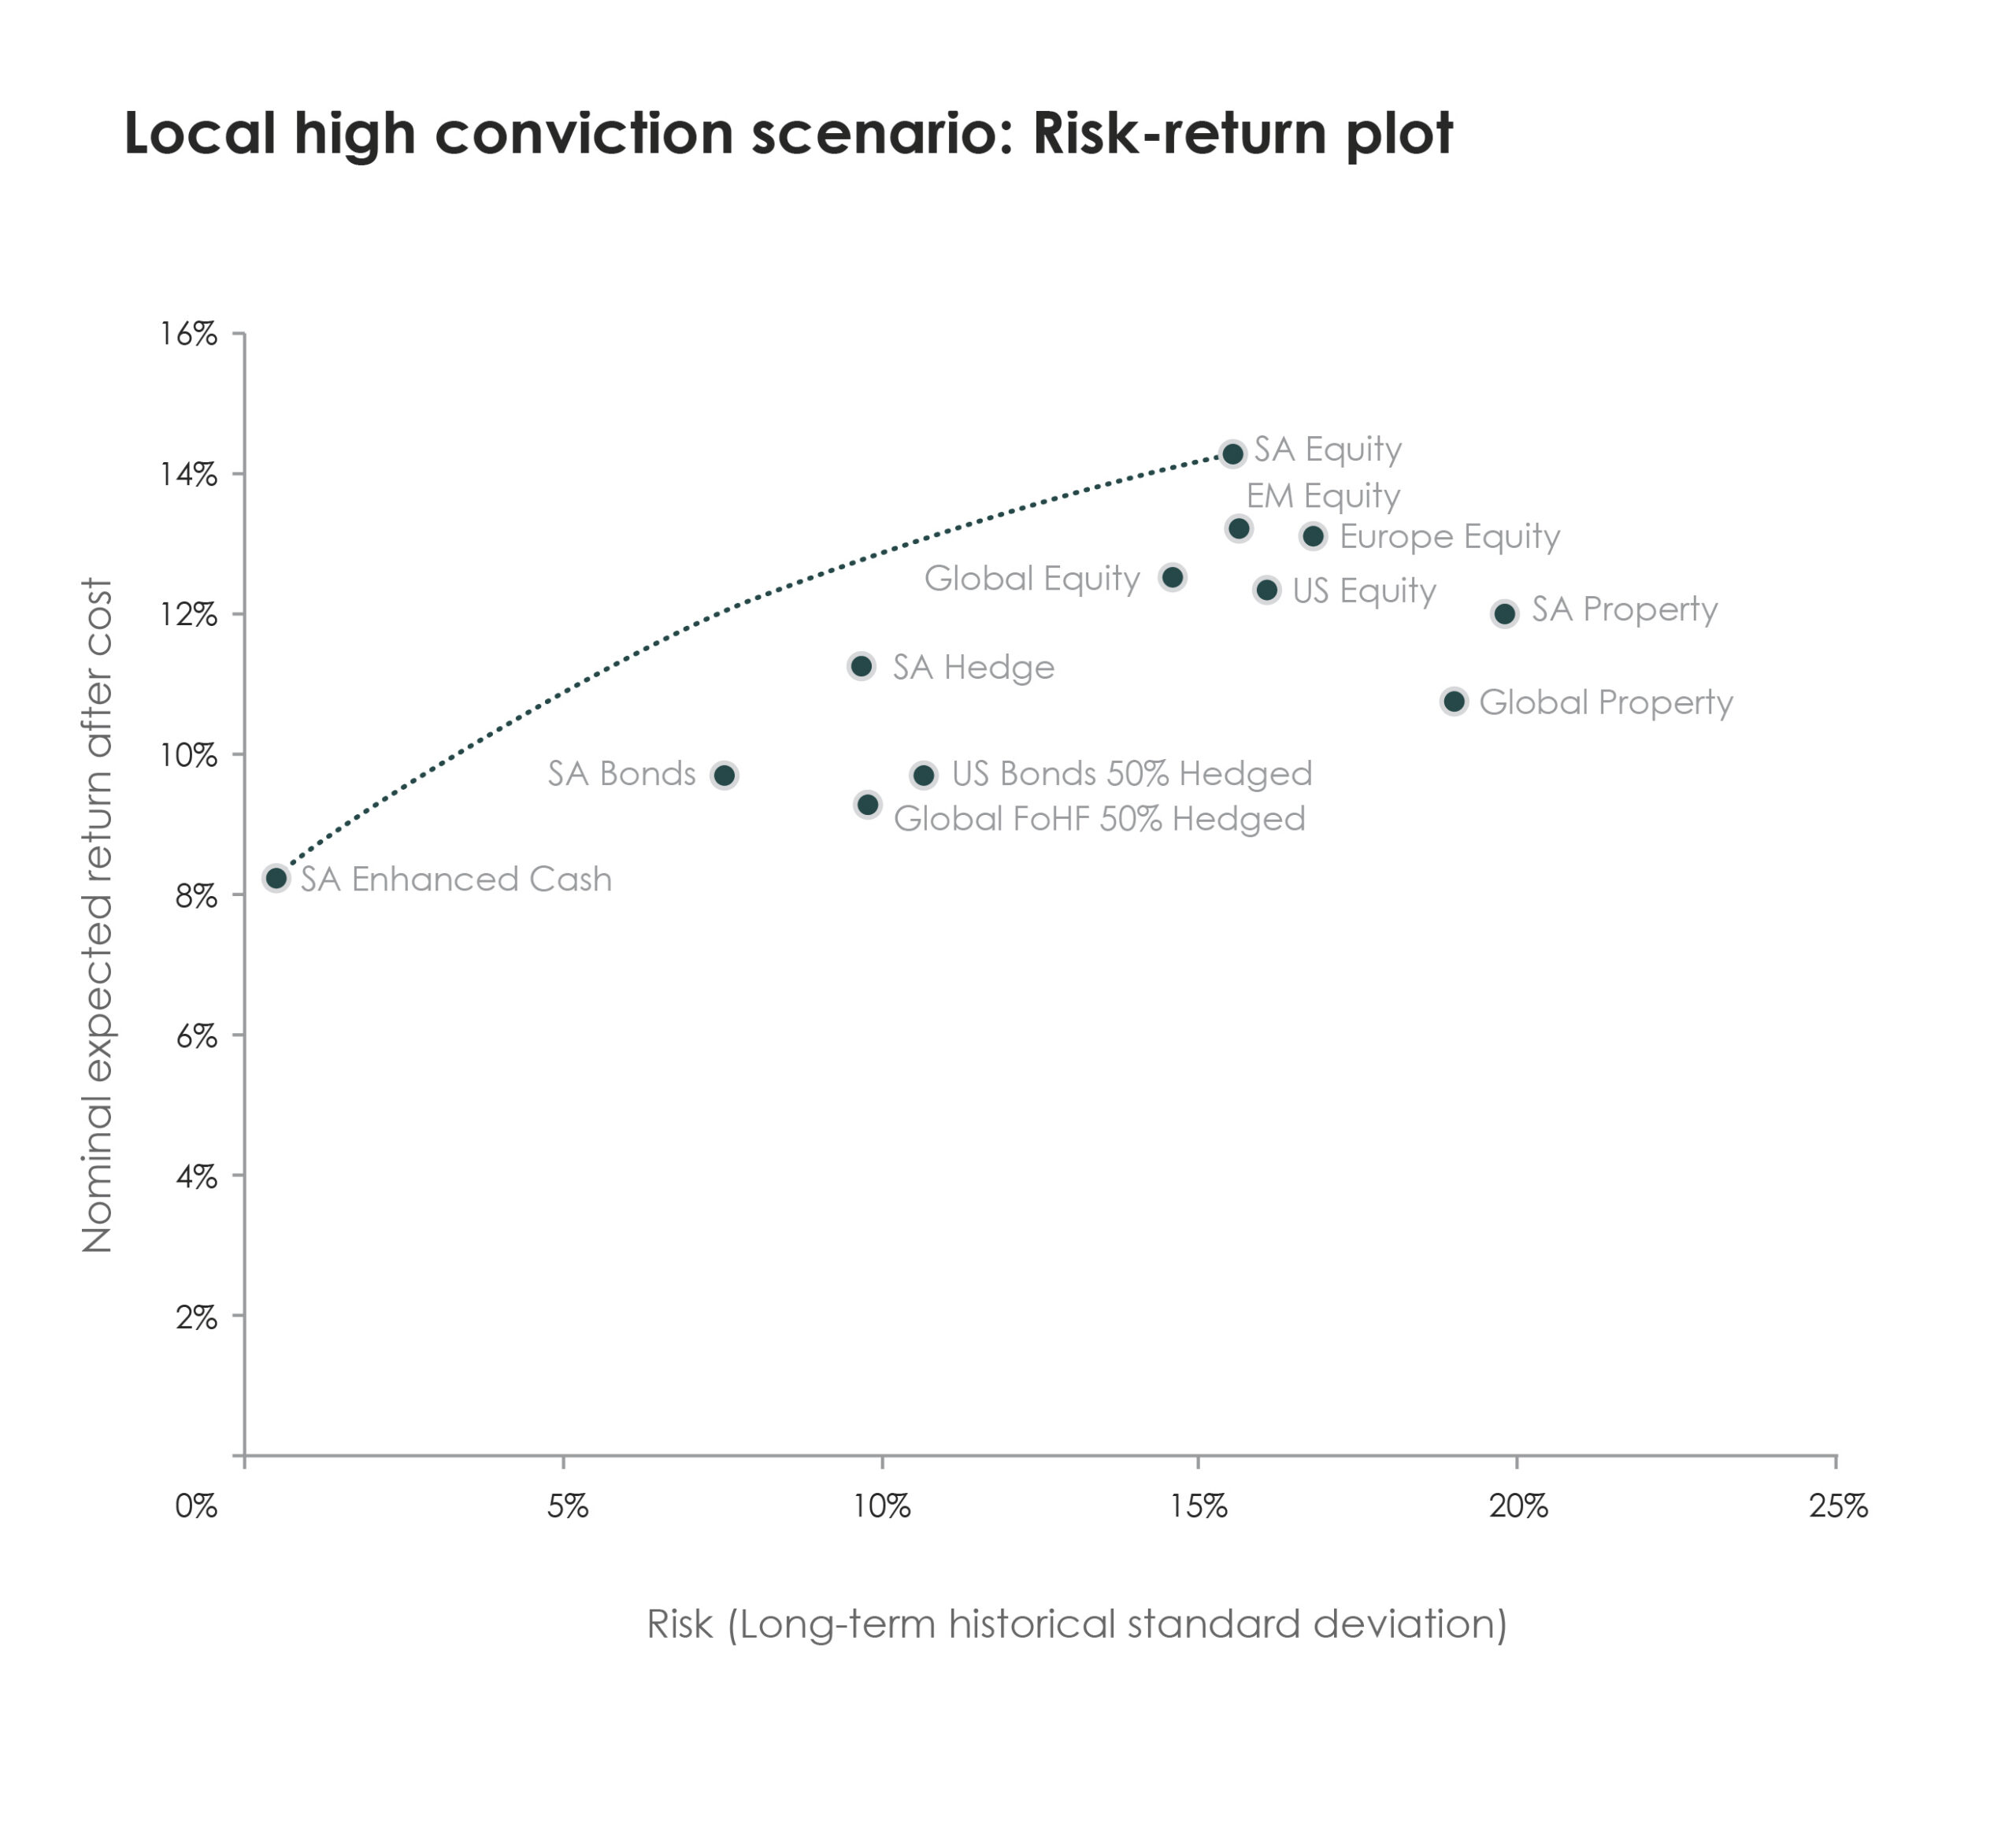
The chart below shows the three-year expected return versus the historical standard deviation of each asset class, based on our High Conviction scenario.
Near-term asset class views
Our investment process is anchored by a High Conviction macroeconomic scenario and the expected returns it produces for various asset classes. While these medium-term valuation signals provide an important foundation for portfolio construction, market behaviour can diverge materially from fair value over shorter periods.
To complement our valuation framework, we incorporate a range of shorter-term indicators, including market dynamics, cross-asset relationships, currency trends and commodity signals. These tools help us identify opportunities and risks that may not yet be reflected in longer-term valuations.
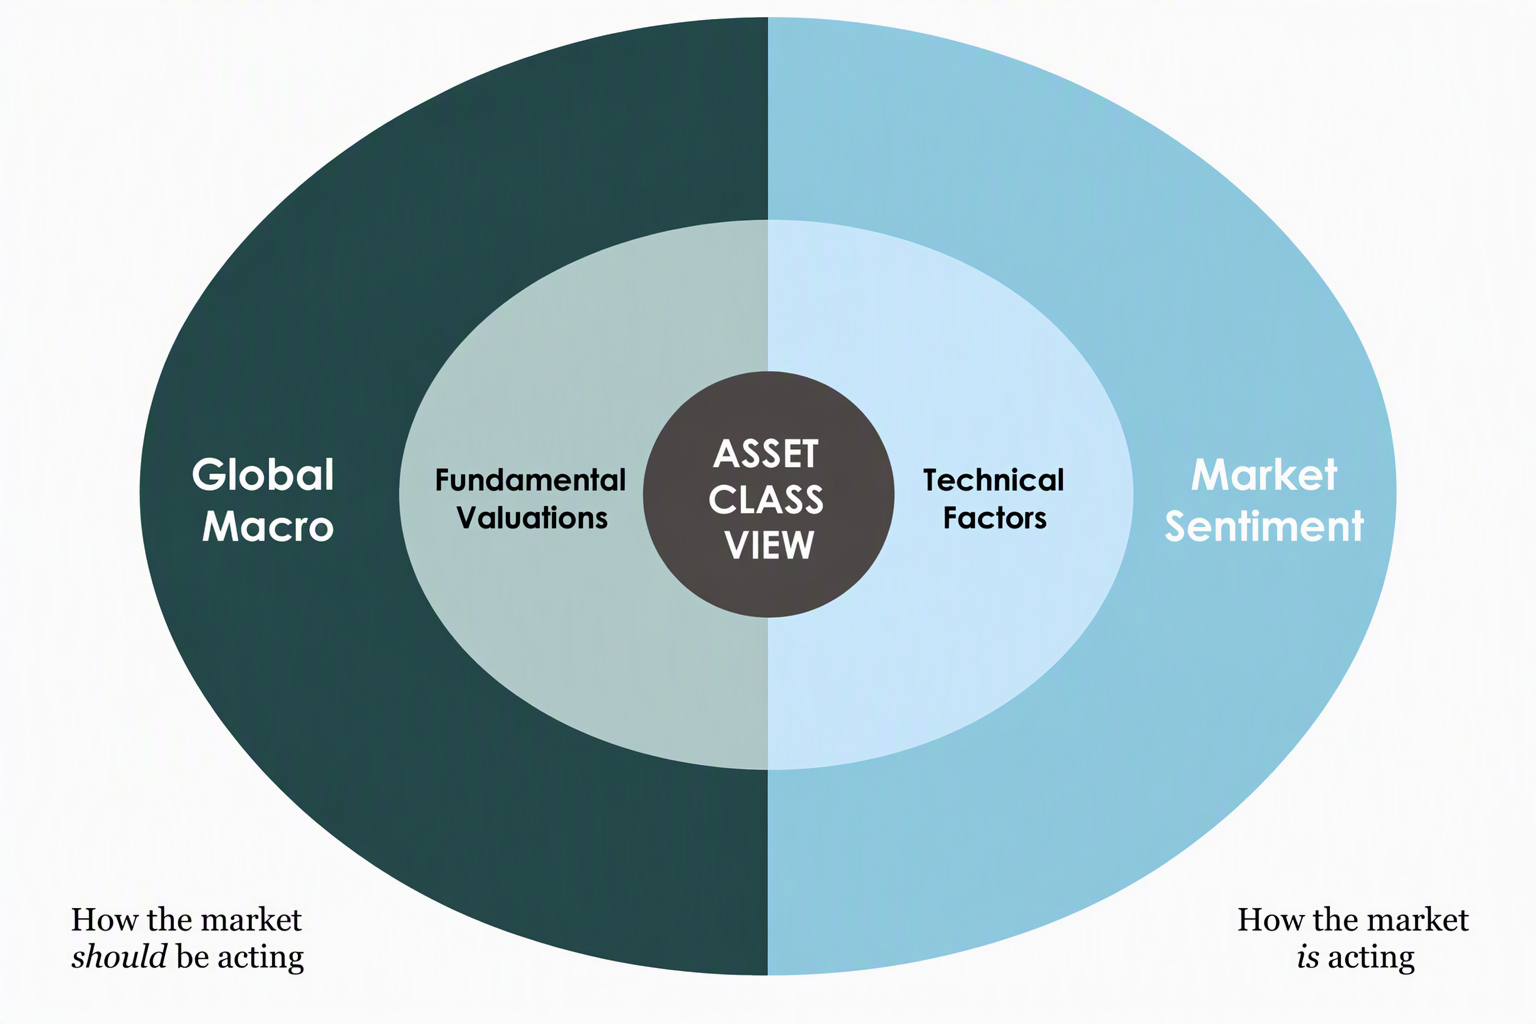
The diagram below gives a visual representation of how these two parts of the process play into each other.
We also integrate the fundamental insights generated by our investment team. Detailed company and sector research helps refine our portfolio positioning and provides an important balance to broader market signals when bottom-up fundamentals differ from top-down expectations.
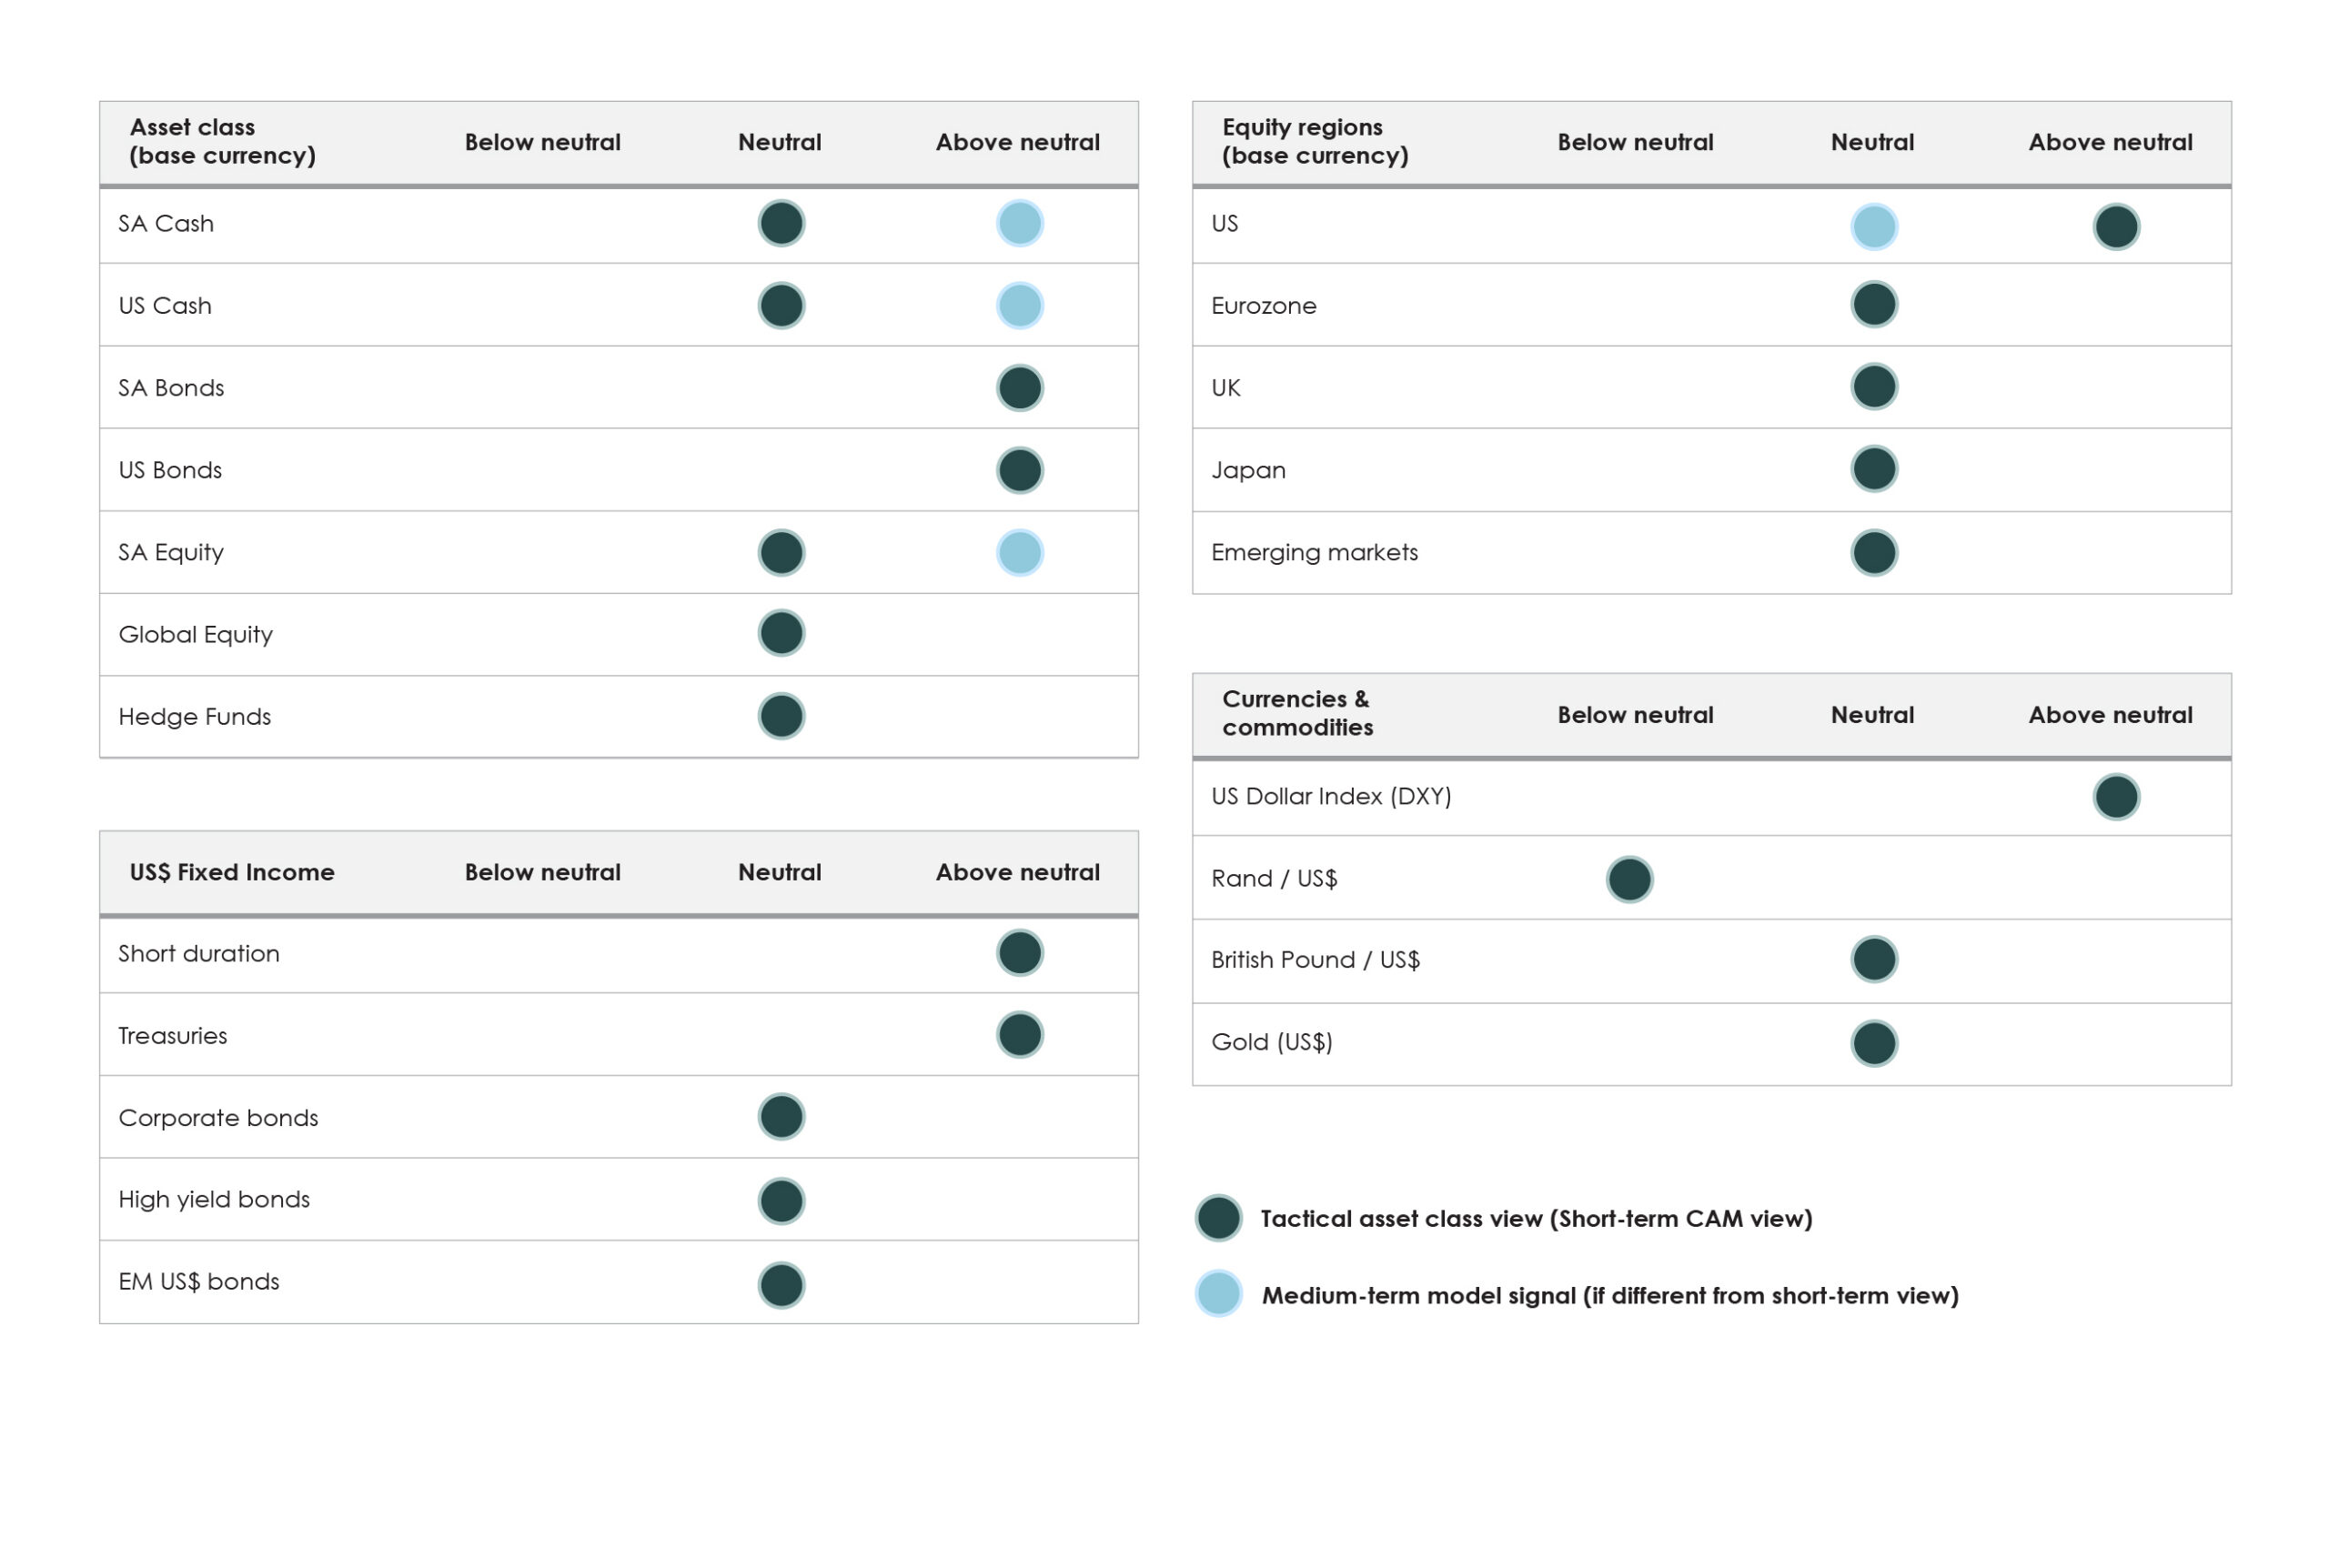
Our latest asset class views are summarised below. The teal blocks represent the short-term tactical views from the team, sometimes with an additional arrow if a Neutral view has more up or downside potential. Where the High Conviction scenario medium-term signals are different from the short-term views, it is indicated in blue. To determine the signal as Neutral or Above and Below, the model compares expected returns to what investors have historically required from these asset classes. For example, a Neutral Outlook implies a real expected return range of 1% to 3% for SA Cash, 2.5% to 5.5% for SA Bonds, and 4.5% to 9.5% for SA Equity. Views are expressed in the base currency of each asset class; currency views are expressed separately.